Mission Statement

The Rant's mission is to offer information that is useful in business administration, economics, finance, accounting, and everyday life. The mission of the People of God is to be salt of the earth and light of the world. This people is "a most sure seed of unity, hope, and salvation for the whole human race." Its destiny "is the Kingdom of God which has been begun by God himself on earth and which must be further extended until it has been brought to perfection by him at the end of time."

Thursday, May 7, 2020

Business Law (part 62)


Only one thing is impossible for God: To find any sense in any copyright law on the planet.

Landlord and Tenant (part A)
 by
 Charles Lamson

A contract whereby one person agrees to lease land or a building to another creates the relationship of landlord and tenant. Such an agreement does not require special words or acts for creation unless the lease lasts for more than a year, in which case it must be in writing. The tenant's temporary possession of the premises and payment of rent for its use constitutes the possession of the premises and payment of rent for its use constitute the chief characteristics that determine the relationship of landlord and tenant. The landlord may retake possession of the property at the end of the lease. 
Justitia Stock Photos - Download 2,300 Royalty Free Photos

The owner of the leased property is known as the landlord, or lessor. The person given possession of the leased property is the tenant, or lessee. The contract or agreement between the landlord and tenant is called a lease (see Illustration 1). The amount the tenant agrees to pay the landlord for the possession of the leased property is called the rent.

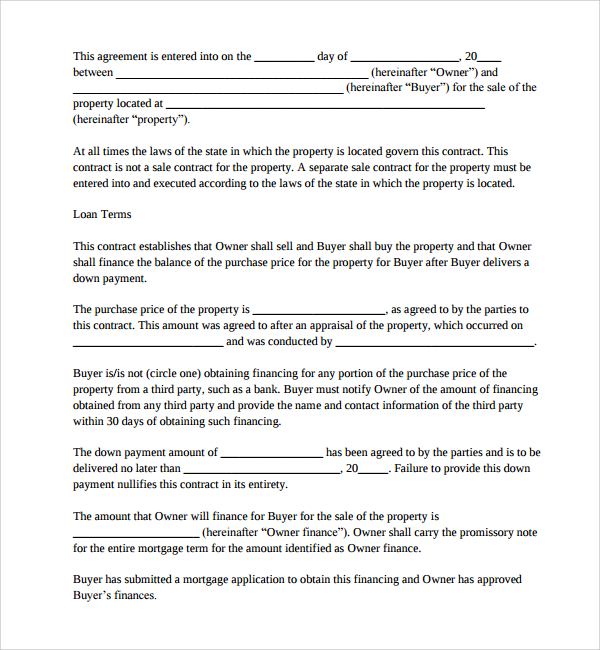
ILLUSTRATION 1 Sample Lease
Sample Lease or Rental Agreement | Rental agreement templates ...

A tenant differs from a lodger or roomer in that the former has the exclusive legal possession of the property, whereas the latter has merely the right to use the premises subject to the control and supervision of the owner.

The Lease

The lease may be oral or written, express or implied, formal or simple, subject, however, to the general a statutory requirement that a lease of land for a term longer than one year must be in writing to be enforceable. If a dispute arises between the tenant and the landlord over their rights and duties, the court will look to the terms of the lease and the general body of landlord and tenant law to determine the decision.

In order to avoid disputes, a lease should be in writing and should cover all the terms of the contract. The parties should include such items as a clear identification of the property, the time and place of payment of rent, the notice required to vacate, the duration of the nature of the tenancy, and any specific provision desired by either party, such as the right of the landlord to show the property to prospective purchasers or an agreement requiring the landlord to redecorate. 

Types of Tenancies

Four separate and distinct classes of tenancies exist, each of which has some rule of law governing it that does not apply to any other type of tenancy. The four classes of tenancies are:
  1. Tenancy for years
  2. Tenancy from year to year
  3. Tenancy at will
  4. Tenancy by sufferance

78 Best Lady Justice (USA) images | Lady justice, Lady, Justice tattoo

Tenancy for Years

A tenancy for years is a tenancy for a definite period of time, whether it is one month, one year, or 99 years. The lease fixes the termination date. However, by law most states limit the length of time a lease may last. A lease for a time greater than the statutory limit is void. The payment of the rent may be by the month even when a tenancy for a specified number of years exists. No notice to terminate the tenancy need to be given by either party when the lease fixes the termination date. Most leases provide that they will continue to run on a year-to-year basis after the termination date, unless the tenant gives notice to the landlord not less than a specified number of days before the termination date that the tenant intends to leave on that date. 

Tenancy from Year to Year

A tenancy for an indefinite period of time with rent set at a yearly amount is known as a tenancy from year to year. Under such a tenancy, a tenant merely pays the rent periodically, and the lease lasts until proper notice of termination has been given. A tenancy of this kind may also be by the month or any other period agreed upon. If by the month, it is called a tenancy from month to month. The length of the tenancy is usually determined by the nature of the rent stated or paid, although there could be a tenancy from year to year with the rent paid quarterly or monthly.

Notice to terminate this type of tenancy must exactly follow the state law governing it. Notice must normally be in writing. In a tenancy from month to month, the law usually requires notice 30 days before a rent due date.

Tenancy at Will

A tenancy at will exists when the tenant has possession of the property for an uncertain period. Either the tenant or the landlord can terminate the tenancy at will, since both must agree to the tenancy. This tenancy, unlike any of the others, automatically terminates upon the death of the tenant or the landlord, if the tenant attempts to assign the tenancy, or the landlord sells the property.

Lady Justice — Art by Christy

Tenancy at Sufferance

When a tenant holds over the tenancy after the expiration of the lease without permission of the landlord, a tenancy at sufferance exists until the landlord elects to treat the tenant as a trespasser or as a tenant. The landlord may treat the tenant as a trespasser, sue for damages, and have the tenant removed by legal proceedings. If the landlord prefers, payment of the rent due for another period may be accepted, and the the tenant's possession may be recognized as rightful. 

Rights of the Tenant

A lease gives the tenant certain rights, as follows:
  1. Right to possession
  2. Right to use the premises
  3. Right to assign or sublease


Right to Possession

By signing the lease, the landlord warrants the right to lease the premises and that the tenant shall have possession during the period of the lease. During the term of the lease, tenant have the same right to exclusive possession of the premises as if they owned the property. If someone questions the owner's right to lease the property, the landlord must defend the tenant's right to exclusive possession. Failure of the landlord to give possession on time or to protect the tenant's rights subject the landlord to liability for damages.

A nuisance that disturbs the tenant's quiet enjoyment of the property often causes disputes between landlords and tenants. Courts have held that failure to remove a dead rat from the wall, failure to stop disorderly conduct on the part of other tenants, and frequent unnecessary entrances upon the property by the landlord or agents constitute acts that destroy the tenant's right to quiet enjoyment and constitute a breach of warranty on the part of the landlord.
Lady Justice by Chinmaya Br (2015) : Painting Acrylic, Oil on ...

If the nuisance existed at the time the tenant leased the property and the tenant knew of its existence, the right to complain would be deemed to have been waived. Also, if the landlord has no control over the nuisance, the tenant cannot avoid the contract even though the nuisance arose subsequent to the signing of the lease. If the landlord fails or refuses to abate a nuisance over which the landlord has control, the tenant not only may terminate the lease, but may sue for damages. In other cases the tenant may seek an injunction compelling the landlord to abate a nuisance.

Right to Use the Premises

Unless the lease expressly restricts this right, the tenant has the right to use the premises in anyway consistent with the nature of the property. A dwelling cannot be converted into a machine shop, nor can a clothing store be converted into a restaurant. Damage to leased property other than that which results from ordinary wear and tear is not permissible. In the case of farming land, the tenant may cut wood for personal use but not to sell.

Right to Assign or Sublease

If the tenant transfers all interest in the lease to another party who agrees to comply with its terms, including the payment of the rent to the landlord, there is an assignment. In an assignment, the assignee pays the rent directly to the landlord. Assignment must include the entire premises. In a sublease, the tenant transfers the premises for a period less than the term of the lease or transfers only a part of the premises. The tenant usually collects the rent from the subtenant and pays the landlord. Ordinarily a written lease prohibits assigning or subleasing the premises unless the lessor gives written consent thereto first. Residential leases commonly restrict the use of the premises to the tenant and the immediate family or to a certain number of persons. Unless the lease expressly prohibits both assignment and subleasing, either may be done. If the lease prohibits only subleasing, then the lease may be assigned.

Joint occupancy closely relates to subleasing. A provision in the lease prohibiting subleasing does not forbid a contract for a joint occupancy. In joint occupancy the tenant does not give up exclusive control of any part of the premises. The tenant merely permits another party to jointly occupy all or a part of the premises. 

*SOURCE: LAW FOR BUSINESS, 15TH ED., 2005, JANET E. ASHCROFT, J.D., PGS. 529-534*

end

Tuesday, May 5, 2020

Business Law (part 61)


I have been committed to carrying out my duties... in accordance with both the letter and spirit of all applicable rules of ethics and canons of conduct.

Real Estate Mortgages (part B)
 by
 Charles Lamson

 Rights of the Mortgagor

 The mortgagor has several rights, including:
  1. Possession of the property
  2. Rents and profits
  3. Cancellation of lien
  4. Redemption
  5. Sale of the property

Lady Justice Digital Art by Erzebet S

Possession of the Property

As the owner of the property, the mortgagor usually has the right to retain possession of the mortgaged property. Upon default the mortgagee usually may take possession to collect rents and profits and apply them to the mortgage debt in compliance with a duty as a fiduciary to the mortgagor. In some states possession cannot be taken, but the appointment of a receiver to collect rent and profits may be obtained.

Rents and Profits

The mortgagor, as the owner of the property, has the right to rent and profits from the property. In the absence of an express agreement to the contrary, the mortgagor has the right to all rents and profits obtained from the mortgaged property. The mortgagor may retain the profits. This rule or any other rule may, of course, be superseded by a contract providing otherwise.

Cancellation of Lien

The mortgagor has the right to have the lien cancelled on final payment. As soon as the mortgagee receives the mortgage, it becomes a lien upon the mortgaged real estate. The clerk in the recorder's office cancels a mortgage lien by entering a notation, usually on the margin, certifying that the debt has been paid and that the lien is canceled. The mortgagee, not the mortgagor, must have this done. If the mortgagee does not, the mortgagor may institute court action to have this cloud removed from the title so that there may be a clear title.

Redemption

The mortgagor has the right to free the mortgaged property from the lien of the mortgage after default, known as the right of redemption. Statutes in most states prescribe a specific time after the foreclosure and sale when this right may be exercised. In order to redeem the property, the mortgagor must pay the amount of the mortgage, the costs of the sale, and any amount paid to protect the purchasers interest in the property, such as taxes or insurance.

Lady Justice Art Print by canotstop | Society6

 Usually only a person whose interests will be affected by foreclosure may exercise the right of redemption. This includes the executor or administrator and heirs of the mortgagor, and frequently a second mortgage or junior lien holder.

Sale of the Property

The mortgagor has a right to sell the property on which a mortgage exists. The purchaser may agree to "assume all the mortgage," which means to be primarily liable for its payment. "Assuming" the mortgage differs from buying the property "subject to the mortgage." In the first case the buyer agrees to be liable for the mortgage obligation as fully as the original mortgagor. If the buyer takes the property "subject to the mortgage" and default occurs, the property may be lost, but no more.

A sale of the mortgaged property does not automatically release the original mortgagor whether the purchaser assumed the mortgage or bought it subject to the mortgage. The mortgagor remains fully liable in both cases.

To excuse the mortgagor from liability under a mortgage, a novation must take place. This can occur if the parties involved sign a written agreement releasing the mortgagor. Courts have also found novations if the mortgagee extends the time of payment for the purchaser of the property without the mortgagor's consent. Accepting an interest payment after the principle of the mortgage has become due constitutes an extension of the mortgage. If the mortgagee does this without the mortgagor's consent, a novation results and releases the mortgagor from all liability under the mortgage. However, the action of the mortgagee must amount to an extension of time of payment. 

Foreclosure

If the mortgagor fails to pay the debt secured by the mortgage when it becomes due, or fails to perform any of the other terms set forth in the mortgage, the mortgagee has the right to foreclose for the purpose of collecting the debt. Foreclosure usually consists of a sale of the mortgaged property. Generally an officer of the court makes the sale under an order of a court. The mortgagor must be properly notified of the foreclosure proceedings. 

Image result for chibi lady justice | Lady justice, Chibi, Anime

Foreclosure literally means "a legal proceeding to shut out all other claims." A first mortgage may not necessarily constitute a first claim on the proceeds of the sale. The cost of foreclosure and taxes always takes precedence over the first mortgage. People who furnish materials for the construction of a house and workers who work on it have a claim under what is known as a mechanics' lien. A mechanics' lien takes precedence over on recorded mortgages. The law varies somewhat among the states, but normally a mortgage recorded before a mechanics' lien attaches has priority. The foreclosure proceedings establish the existence of all prior claims and the order of their priority. Foreclosure proceedings are fixed by the statute and therefore vary in different states.

If the proceeds of the sale of mortgage property exceed the amount of the debt and the expenses of foreclosure the surplus must be used to pay off any other liens such as second mortgages. Any money remaining belongs to the mortgagor.

If a deficiency results, however, the mortgagee may secure a deficiency judgment for this amount. In that case the unpaid balance of the debt will stand as a claim against the mortgage here until payment of the debt.

When the mortgagor has given a mortgage for the purpose of purchasing the property, some states limit the amount of a deficiency judgment. The deficiency cannot be greater than the amount by which the debt exceeds either the fair market value or the selling price, whichever amount is smaller. This gives protection to the mortgagor from the mortgagee buying the property at foreclosure for a very low price. For example, suppose A mortgages property to B for $50,000, and the value of the property declines to $40,000. A defaults and B forecloses. B buys the property at foreclosure for $30,000. 
B may obtain a deficiency Judgment of $10,000 because it is the lesser of the two amounts.

Colored Justice Tattoo Design

Assignment of the Mortgage

The rights of the mortgagee under the mortgage agreement may be assigned. The assignee, the purchaser, obtains no greater rights than the assignor had. To be protected, the assignee should require the assignor to produce an estoppel certificate signed by the mortgagor. This certificate should acknowledge that the mortgagor has no claims of any kind in connection with the mortgage. This would bar the mortgagor from subsequently claiming the right of offset.

The assignee of a mortgage should have this assignment recorded. In the event that the mortgagee assigns the mortgage to more than one party, the one who records an assignment first has preference. This can be important when the proceeds are not adequate to pay both assignees.

Deed of Trust

In a number of states, parties commonly use a deed of trust instead of a mortgage for securing a debt with real estate. A mortgage involves two parties, a debtor and  a creditor. A deed of trust involves three parties. It conveys title to the property to a disinterested party, called a trustee. The trustee holds the property in trust for the benefit of the creditor. Most courts treat a deed of trust like a mortgage. If a default in payment occurs, the trustee forecloses on the property and applies the proceeds to the payment of the debt. The right to redeem under a deed of trust, when it exists, is similar to the right of redemption under a mortgage.

The advantage to the creditor in using a deed of trust instead of a mortgage is in the power held by the trustee. In the event a mortgagor defaults in the payments, the mortgagee who holds an ordinary mortgage can foreclose. In most states, however, the mortgagee must go into court and have a judicial foreclosure in order to have the mortgaged property sold to satisfy the debt. A trustee of a deed of trust may sell the mortgaged property at public auction if the debtor defaults. No time-consuming court foreclosure proceedings are necessary. Hence, the property can be sold more quickly at a trustee's sale.

Mortgage Insurance

Private companies and several agencies of the federal government insure or guarantee mortgagors against their fault by the mortgagor. The insurance lasts for the term of the mortgage. The government agrees to pay in case of default by the mortgagor in order to make it easier for some people to obtain a mortgage. The most frequently used government programs are those administered by the Federal Housing Administration (FHA) and the Veterans Administration (VA).

Lady Justice by Mg3-Kiryu on DeviantArt

FHA-insured mortgages require a smaller down payment than conventional mortgages. Anyone who meets the financial qualifications may obtain an FHA loan. Because FHA mortgages are insured, the interest rate is slightly less than for a conventional mortgage. The FHA sets a maximum amount that may be mortgaged. The FHA bases this amount on the average sale price in the area for a home. The mortgagor pays premiums for this mortgage insurance.

The VA guarantees mortgages for people who have served on active duty in the armed forces for a minimum of time. The mortgage must be on owner-occupied property. The VA charges the mortgagor a percentage of the loan amount for its guarantee. It sets the interest rate charged. As a benefit to veterans, it sets this rate less than the market rate for conventional loans. A VA mortgage may be for up to 100 percent of the value of the real estate. This means no down payment is required. The maximum loan amount is $144,000. 

INTERNET RESOURCES FOR BUSINESS LAW

Name 
Web Addresses
Links
U.S Department of Housing and Urban Development (HUD)
HUD provides information on real property and planning issues for both consumers and businesses. HUD also provides information on the Fair Housing Act and the Civil Rights Act.
HUD USER
HUD USER, PD&R's information source for housing and community development researchers and policymakers, provides federal government reports and information on housing policy and programs, building technology, economic development, urban planning, and other housing related topics.
Legal Information Institute (LII)---Land-Use Law Materials
LII, maintained by Cornell Law School, provides an overview a land-use law, links to statutes, federal and state judicial court decisions, and other materials.
Themis | Greek goddess | Britannica
Themis - Justice | Arte grega antiga, Arte antiga, Arte grega
Themis - Atlas

Color Ink Lady Justice Tattoo Design For Girls

*SOURCE: LAW FOR BUSINESS, 15TH ED., 2005, JANET E. ASHCROFT, J.D., PGS. 520-524, 527*

end

Sunday, May 3, 2020

Business Law (part 60)


It is legal because I wish it.


Real Estate Mortgages (part A)
by
 Charles Lamson

 A mortgage is an interest in real estate given to secure the secure the payment of a debt. The mortgage does not constitute the debt itself but the security for the debt. If the debt is not paid the property may be sold to pay the debt. Land or any interest in land may be mortgaged. Land maybe mortgage separately from the improvements, or the improvements may be mortgaged apart from the land. A person who gives a mortgage as a security for a debt is a mortgagor. A person who holds a mortgage as property for a debt is a mortgagee.

Justice Digital Art by Emma Alvarez

The mortgagor normally retains possession of the property. In order for the mortgagee to obtain the benefit of the security, the mortgagee must take possession of the premises upon default or sell the mortgaged property at a foreclosure sale. In some states, the mortgagee may not take possession of the property upon default but may obtain the appointment of a receiver to collect the rents and income. If the sale of the property brings more than the debt and the costs, the mortgagor must be paid the balance. 

The Mortgage Contract

A mortgage must be in writing. The contract, as a rule, must have the same form as a deed, which means it must be acknowledged. The mortgage, like all other contracts sets forth the right and the duties of the contracting parties (see Illustration 1). As a type of contract, mortgages are interpreted according to contract law rules.

ILLUSTRATION 1 Mortgage Contract
FREE 12+ Sample Mortgage Agreement Templates in PDF | MS Word ...

A mortgagor normally gives a mortgage to raise money for the purchase price of real estate, but it may be given for other reasons. One may borrow money for any reason and secure the loan by a mortgage. One may assume a contingent liability for another, such as becoming a surety, and receive a mortgage as security.

The effect of a mortgage is to be a lien against the mortgaged property. A lien is an encumbrance or claim against property. The lean of the mortgage attaches to the property described in the mortgage. A mortgage generally also provides that the lien attaches to additions thereafter made to the described property; for example, the lien of the mortgage attaches to personal property, which thereafter becomes a fixture. A clause purporting to make the security clause of a mortgage becomes a fixture. A clause purporting to make the security clause of a mortgage cover future debts will be valid if the parties intended it to cover future debts.

Exhibit 17: Lady Justice | Lady justice, Justice tattoo, Law tattoo

Recording

Depending upon the law of the state in which the land lies, the mortgage gives the mortgagee either a lien on the land or title to the land. The mortgagor's payment of the debt divests or destroys this title or lien. Recording the mortgage protects the mortgagee against subsequent creditors, since the public record normally constitutes notice to the whole world as to the mortgagee's rights. There may be both a first mortgage and subsequent, or junior, mortgages. The mortgage recorded first normally has preference. This is not true of when actual notice of a prior mortgage exists. However, a purchase money mortgage has preference over other claims arising through the mortgagor. The mortgage is also recorded to notify its subsequent purchasers that as much of the purchase price as is necessary to pay off the mortgage must be paid to for the mortgagee. Recording must be proper, otherwise the purpose of the mortgagee providing notice to others cannot be accomplished. 

Duties of the Mortgagor

The mortgagor assumes three definite duties and liabilities when placing a mortgage upon real estate. These pertain to:
  1. Interest and principal
  2. Taxes, assessments, and insurance premiums
  3. Security of the mortgagee

Interest and Principal

The mortgagor must make all payments of interest and principal as they become due. Most mortgages call for periodic payments, such as monthly, semiannually, or annually. These payments are used to pay all accrued interest to the date of payment, and the mortgagee applies the balance on the principal. Other mortgages call for periodic payment of interest and for the payment of the entire principal at one time. In either case, a failure to pay either the periodic payments of interest and principal or of interest only constitutes a default. A default gives the mortgagee the right to foreclose. Most mortgages contain a provision that if the mortgagor does not make an interest or principal payment when due or within a specified time after due, the mortgagee may declare the entire principal immediately due. This is known as an acceleration clause.

Card of the Day – Justice – Monday, June 12, 2017 – Tarot by Cecelia

If the mortgagor wishes to pay off the mortgage debt before the due date so as to save interest, that right must be reserved at the time the mortgage is given. 

Taxes, Assessments, and Insurance Premiums

The mortgagor, who is the owner of the land regardless of the form of the mortgage, must continue to make such payments as would be expected of an owner of land. The mortgagor must pay taxes and assessments. If the mortgagor has not paid the taxes and assessments, the mortgagee must pay them and compel a reimbursement from the mortgagor. If the mortgage contract requires the mortgagor to pay these charges, a failure to pay them becomes a default.

The law does not require the mortgagor to keep the property insured nor to insure it for the benefit of the mortgagee. This duty cannot be imposed on the mortgagor by the mortgage contract. Both the mortgagor and mortgagee have an insurable interest in the property to the extent of each one's interest or maximum loss.

Security of the Mortgagee

The mortgagor must do not act that will materially impair the security of the mortgagee. Cutting timber, tearing down buildings, and all acts that waste the assets impair the security and give the mortgagee the right to seek legal protection. Some state statutes provide that any one of these acts constitutes a default. This gives the mortgagee the right to foreclose. Other statues provide only that the mortgagee may obtain an injunction in a court of equity enjoining any further impairment. Some states provide that for the appointment of a receiver to prevent waste. Many state laws also make it a criminal offence to willfully impair the security of mortgaged property. 

Card of the Day for April 7, 2020 in 2020 | Justice tarot, Tarot ...

*SOURCE: BUSINESS FOR LAW, 15TH ED., 2005, JANET E. ASHCROFT. J.D., PGS. 516-520*

end

Rosary from Lourdes - 02/12/2025