Inventory Management
In a manufacturing company, inventory is usually divided into the three basic categories: raw materials used in the product; work in progress, which reflects partially finished products; and finished goods, which are ready for sale. All these forms of inventory need to be financed, and their efficient management can increase a firm's profitability. The amount of inventory is not always totally controlled by company management because it is affected by sales, production, and economic conditions.
Because inventory is the least liquid of current assets, it should provide the highest yield to justify the investment. While the financial manager may have direct control over cash management, marketable securities, and accounts receivable, control over inventory policy is generally shared with production management and marketing. Let us examine some key factors influencing inventory management.
Level versus Seasonal Production
A manufacturing firm must determine whether a plan of level or seasonal production should be followed. Level production means that a company will produce at a constant rate regardless of the demand level. While level even production throughout the year allows for maximum efficiency and the use of manpower and machinery, it may result in unnecessarily high inventory buildups before shipment, particularly in a seasonal business. For example, a bathing suit manufacturer would not want 10,000 suits in stock in November.
If we produce on a seasonal basis, the inventory problem is eliminated but we will then have unused capacity during slack periods. Furthermore, as we shift to maximum operations to meet seasonal needs, we may be forced to pay overtime wages to labor and to sustain other inefficiencies as equipment is overused.
We have a classic problem in financial analysis. Are the cost savings from level production sufficient to justify the extra expenditure in carrying inventory? Let us look at a typical case.
Though $30,000 more will have to be invested in the average inventory under level production (first line), $10,000 will be saved in operating costs (second line). This represents a 33 percent return on investment. If the required rate of return is 10 percent, this would clearly be an acceptable alternative.
Inventory Policy in Inflation and Deflation
The price of copper went from $1.40 to $0.50 a pound and back up again, all the way to where its now at $3.15 per pound during the last three and a half decades. Similar price instability has occurred in wheat, sugar, lumber, and a number of other commodities. Only the most astute inventory manager can hope to prosper in this type of environment. The problem can be partially controlled by taking moderate inventory positions (do not fully commit at one price).
Another way of protecting an inventory position would be by hedging with a futures contract to sell at a stipulated price some months from now.
Rapid price movements in inventory may also have a major impact on the reported income of the firm. A firm using FIFO (first in, first out) accounting may experience large inventory profits when old, less-expensive inventory is written off against new high prices in the marketplace. The benefits may be transitory, as the process reverses itself when prices decline.
The Inventory Decision Model
Substantial research has been devoted to determining optimum inventory size, order quantity, usage rate, and similar considerations. An entire branch in the field of operations research is dedicated to the subject.
In developing an inventory model, we must evaluate the two basic costs associated with inventory: the carrying costs and the ordering costs. Through a careful analysis of both of these variables, we can determine the optimum order size that minimizes costs.
Carrying Costs Carrying costs include interest on funds tied up in inventory and the costs of warehouse space, insurance premiums, and material handling expenses. There is also an implicit cost associated with the dangers of obsolescence or perishability and rapid price change. The larger the order we place, the greater the average inventory we will have on hand, and the higher the carrying costs.
Ordering Costs As a second factor, we must consider the cost of ordering and processing inventory into stock. If we maintain a relatively low average inventory in stock, we must order many times and total ordering costs will be high. The opposite patterns associated with the two costs are portrayed in Figure 9.
Figure 9 As the order size increases, carrying costs go up because we have more inventory on hand. With larger orders, of course, we will order less frequently and overall ordering costs will go down. The trade-off between the two can best be judged by examining the total cost curve. At Point M on that curve, we have appropriately played the advantages and disadvantages of the respective costs against each other. With larger orders, carrying costs will be excessive, while at a reduced order size, constant ordering will put us at an undesirable high point on the ordering cost curve.
Economic Ordering Quantity
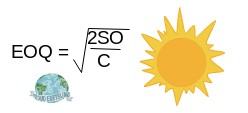
The question becomes, how do we mathematically determine the minimum point (M) on the total cost curve? We may use the following formula.
EOQ is the economic ordering quantity, the most advantageous amount for the firm to order each time. We will determine this value, translate it into average inventory size, and determine the minimum total cost amount (M). The terms in the EOQ formula are defined as follows:
Let us assume that we anticipate selling 2000 units; it will cost us $8 to place each order; the price per unit is $1, and with a 20 percent carrying cost to maintain the average inventory; the carrying charge per unit is $0.20. Plugging these values into our formula, we show:
The optimum order size is 400 units. On the assumption that we will use up inventory at a constant rate throughout the year, our average inventory on hand will be 200 units, as indicated in Figure 10. Average inventory equals EOQ/2.
Figure 10
Our total costs with an order size of 400 and an average inventory size of 200 units are computed in Table 5.
Table 5 Total costs for inventory
Point M in Figure 9 above can be equated to a total cost of $80 at an order size of 400 units. At no other point can we hope to achieve lower costs. The same basic principles of total cost minimization that we have applied to inventory can be apply to other assets as well. For example, we may assume cash has a carrying cost (opportunity cost of lost interest on marketable securities as a result of being in cash) and an ordering cost (transaction costs of shifting in and out of marketable securities) and then work toward determining the optimum level of cash. In each case we are trying to minimize the overall costs and increase profit.
Safety Stock and Stock Outs
In our analysis thus far we have assumed we would use inventory at a constant rate and would receive new inventory when the old level of inventory reached zero. We have not specifically considered the problem of being out of stock.
A stock-out occurs when a firm is out of a specific inventory item and is unable to sell or deliver the product. The risk of losing sales to a competitor may cause a firm to hold a safety stock to reduce this risk. Although the company may use the EOQ model to determine the optimum order quantity, management cannot always assume that delivery schedules of suppliers will be constant or that there will be delivery of new inventory when old inventory reaches zero. A safety stock will guard against late deliveries due to weather, production delays, equipment breakdowns, and the many other things that can go wrong between the placement of an order and its delivery.
A minimum safety stock will increase the cost of inventory because the carrying cost will rise. This cost should be offset by eliminating lost profits on sales due to stock outs and also by increased profits from unexpected orders that can now be filled.
In the prior example, if a safety stock of 50 units were maintained, the average inventory figure would be 250 units.
The amount of safety stock that a firm carries is likely to be influenced by the predictability of inventory usage and the time period necessary to fill inventory orders. The following discussion indicates safety stock may be reduced in the future.
Just-in-Time Inventory Management
Just-in-time inventory management (JIT) was designed for Toyota by the Japanese firm Shigeo Shingo and found its way to the United States. Just-in-time inventory management is part of the total production concept that often interfaces with a total quality control program. A JIT program has several basic requirements: (1) quality production that continually satisfies customer requirements; (2) close ties between suppliers, manufacturers, and customers; and (3) minimization of the level of inventory.
Usually suppliers are located near manufacturers and are able to make orders in small lot sizes because of short delivery times. One side effect has been for manufacturers to reduce their number of suppliers to assure quality as well as to ease the complexity of ordering and delivery. Computerized ordering/inventory tracking systems both on the assembly line and in the supplier's production facility are necessary for JIT to work.
Cost Savings from Lower Inventory Cost savings from lower levels of inventory and reduced financing costs are supposed to be the major benefits of JIT.
Other Benefits There are other, not so obvious cost savings to just-in-time inventory systems. Because of reduced warehouse space for inventory, some plants in the automotive industry have reduced floor space by 70% over the more traditional plants that warehoused inventory. This saves construction costs and reduces overhead expenses for utilities and manpower. The JIT systems are aided by the Internet and electronic data interchange systems (EDI) between suppliers and production and manufacturing departments. EDI reduces rekeying errors and duplication of forms for the accounting finance functions. Reductions in costs from quality control are often overlooked by financial analysts because JIT prevents defects rather than detecting poor quality; therefore, no cost savings are recognized. One last item is the elimination of waste, which is one of the side benefits of a total quality control system coupled with just-in-time inventory systems.
 It is important to realize that the just-in-time inventory system is very compatible with the concept of economic ordering quantity. The focus is to balance reduced carrying costs from maintaining less inventory with increased ordering costs. Fortunately electronic data interchange minimizes the impact of having to place orders more often.
The Downside of JIT When JIT methods work as planned, firms are able to maintain very little inventory, reduce warehouse storage space, and reduce the cost of financing a large inventory. Some JIT management systems allow inventory levels ranging from 1 hour's worth of parts to a maximum of 16 hours' worth. However, there are costs associated with an integrated JIT system. Walmart, the world's largest retailer, is said to have one of the largest computer systems in the United States (second only to the Pentagon) (Block & Hirt, 2005, p. 200). These costs should not be overlooked.
In Sum
It seems like a simple concept, but it needs to be stated that the company that manages its current assets efficiently will minimize (or optimize) its investment in them, thereby freeing up funds for other corporate uses. The result will be higher profitability and return on total assets for the firm.
*MAIN SOURCE: BLOCK & HIRT, 2005, FOUNDATIONS OF FINANCIAL MANAGEMENT, 11TH ED., PP. 194-200*
end |